Executive Summary
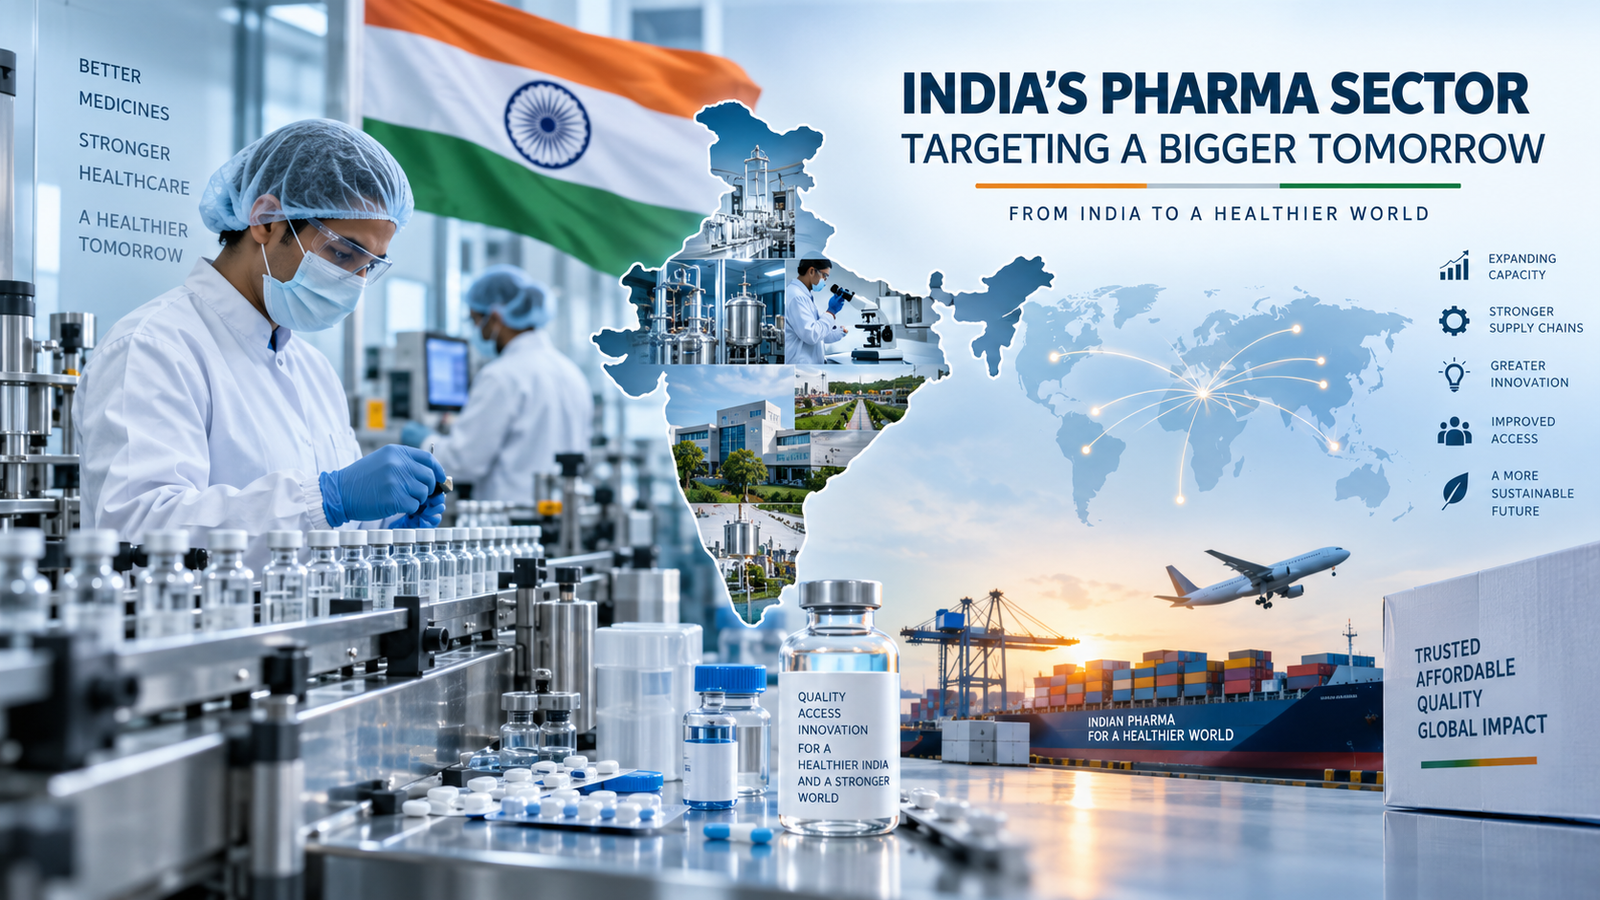
India’s pharmaceutical industry is entering a period in which growth will increasingly depend on capability rather than volume alone. Strong exports, government-backed manufacturing incentives, supply-chain diversification, increasing demand for complex therapies and a renewed push toward R&D are creating a wider opportunity than the traditional generics model.
The opportunity is substantial. India’s pharmaceutical exports reached approximately US$30.47 billion in FY2024–25, growing 9.4% year on year, while the Economic Survey 2025–26 reported sector turnover of about ₹4.72 lakh crore in FY2024–25. At the same time, government programmes are directing capital toward domestic APIs, complex products, R&D infrastructure and innovation.
But expansion should not be confused with automatic success. India’s next competitive advantage will depend on regulatory reliability, quality systems, scientific talent, advanced manufacturing, capital productivity and the ability to move from being a low-cost supplier to becoming a trusted, high-value partner in global pharmaceutical supply chains.
The beginning of a different pharmaceutical cycle
For several decades, the Indian pharmaceutical story was relatively easy to explain.
The country developed an extraordinary capability to manufacture medicines at competitive cost, built a large generic-drug industry and gradually established itself as a major supplier to regulated and emerging markets. That model created globally recognised companies, manufacturing clusters and a deep pool of scientific and technical talent.
But the next phase is less straightforward.
The question is no longer whether India can manufacture medicines cheaply. It clearly can. The more important question is whether India can capture a larger share of the value created before, during and after manufacturing.
That means moving further into complex generics, biosimilars, specialty medicines, injectables, high-value APIs, peptides, biologics, contract research and development, and increasingly sophisticated manufacturing.
There are already signs that this shift is underway.
India’s pharmaceutical exports reached about US$30.47 billion in FY2024–25, up 9.4% from the previous year. Pharmexcil data show that formulations and biologicals accounted for approximately three-quarters of exports, while bulk drugs and intermediates contributed about 16%. The United States remained the dominant destination, accounting for more than one-third of total exports.
The scale is significant. But perhaps more important is what the numbers reveal about India’s role in the global pharmaceutical system.
India is no longer simply competing for individual generic-product opportunities. It is increasingly competing for long-term positions in global supply chains.
That distinction will matter enormously over the next decade.
From volume to value
The strongest structural change taking place in Indian pharma is the gradual movement from a predominantly volume-driven model toward a more value-oriented one.
The Economic Survey 2025–26 explicitly identifies this direction, noting India’s movement toward complex generics, biosimilars and innovation as the industry seeks to move up the value chain.
This transition is economically important.
A conventional generic can be highly competitive but may also face intense price erosion once multiple suppliers enter the market. Complex products are different. They require more sophisticated development capabilities, specialised manufacturing infrastructure, regulatory expertise and, in many cases, higher technical barriers to entry.
That creates the possibility of better margins and longer-lasting competitive advantages.
India has already demonstrated capabilities in areas such as oncology, respiratory products, injectables, biosimilars and difficult-to-manufacture formulations. The opportunity now is to broaden that base.
Peptides, long-acting injectables, complex biologics, advanced drug-delivery systems and specialised sterile manufacturing are likely to attract increasing attention.
But moving into these areas requires more than installing another production line.
The companies that succeed will need strong process development, analytical capability, technology transfer, intellectual property expertise, regulatory science and reliable quality systems.
The competitive equation is therefore changing from:
Cost + Capacity
to:
Cost + Capacity + Complexity + Compliance + Speed + Scientific Capability.
That is a much harder equation to execute.
The China+1 opportunity is real — but India should not mistake it for a guarantee
Global pharmaceutical companies have spent the last several years reassessing supply-chain concentration.
Geopolitical tensions, pandemic-related disruptions, logistics risks and growing concerns around supply continuity have encouraged multinational companies to diversify manufacturing and sourcing.
This has created an opportunity for India.
Indian companies already possess experience supplying highly regulated markets, a large chemistry talent pool and a substantial base of internationally approved manufacturing facilities. CRISIL estimated that India’s CRDMO sector could grow 13–15% in the relevant fiscal year, supported by global supply-chain diversification. It also highlighted India’s chemistry capabilities, US FDA-approved plants and relatively lower R&D and manufacturing costs as competitive strengths.
But there is an important qualification.
India does not need to replace China across the entire pharmaceutical supply chain.
That is neither realistic nor necessary.
China has enormous scale in several chemical and pharmaceutical-input categories. India’s opportunity is to establish itself as a second strategic pillar for global pharmaceutical companies — particularly where quality, regulatory confidence, scientific capability and supply-chain resilience matter as much as price.
The distinction is crucial.
The winning Indian company may not be the one offering the lowest manufacturing price. It may be the one that gives a global customer confidence that the product will be developed correctly, manufactured consistently, released on schedule and accepted by regulators.
That is a different business proposition.
APIs: strategic necessity meets commercial reality
India’s dependence on imported pharmaceutical raw materials has been discussed for years, particularly in relation to China.
The policy response has become more substantial.
The government’s PLI programme for critical KSMs, drug intermediates and APIs carries an outlay of ₹6,940 crore. By August 2025, the government reported 48 projects across 33 APIs, drug intermediates and KSMs, with fresh manufacturing capacity established at 28 greenfield locations.
The broader pharmaceutical PLI programme is also generating significant investment. By December 2025, cumulative investment under the pharmaceutical PLI scheme had reached ₹41,943 crore, compared with committed investment of ₹17,275 crore. Cumulative sales of products covered under the scheme were reported at ₹3,35,036 crore.
These are meaningful numbers.
Yet domestic production of APIs will not automatically make India more competitive.
API economics are unforgiving. Scale, yield, energy costs, environmental compliance, solvent recovery, effluent treatment, process efficiency and reliable access to starting materials all influence the final cost.
An API plant that is strategically important but structurally uncompetitive cannot remain viable simply because it replaces an import.
The longer-term opportunity is therefore to create globally competitive API ecosystems, not merely protected domestic capacity.
That will require integration between chemistry, engineering, utilities, environmental management and manufacturing excellence.
CDMO and CRDMO: potentially India’s most interesting growth story
Perhaps no segment better illustrates India’s changing pharmaceutical opportunity than contract development and manufacturing.
The global pharmaceutical industry increasingly wants partners that can do more than manufacture a product according to a specification.
It wants companies that can contribute to process development, analytical development, scale-up, formulation, clinical supply, commercial manufacturing and regulatory support.
This is where the distinction between a CDMO and a strategic development partner becomes important.
India has several natural advantages: chemistry expertise, a large technical workforce, established pharmaceutical manufacturing infrastructure and relatively competitive development costs.
The opportunity is already attracting capital.
CRISIL expects Indian pharma CRDMO revenues to continue growing at double-digit rates, with healthy margins supporting further capital expenditure.
Recent industry analysis has also pointed to a potentially much larger long-term opportunity for India’s CRDMO sector, provided companies can move beyond transactional manufacturing and develop deeper relationships with global innovators.
That last point deserves attention.
India’s CDMO future will not be determined simply by how many reactors, manufacturing suites or square metres of cleanroom space are added.
It will depend on whether customers trust Indian partners with critical programmes.
That requires confidentiality, intellectual property protection, technical depth, project management, regulatory consistency, data integrity and the ability to deliver repeatedly.
In other words, reliability becomes a product.
R&D: the difficult transition from imitation to innovation
India’s pharmaceutical industry has historically been exceptionally good at development, process chemistry and commercialisation of known molecules.
Creating entirely new medicines is a different challenge.
Drug discovery requires long development cycles, significant capital, specialised scientific talent and a tolerance for failure. It also requires close interaction between universities, research institutions, biotechnology companies and pharmaceutical manufacturers.
India is attempting to strengthen that ecosystem.
The Promotion of Research and Innovation in Pharma-MedTech Sector (PRIP) scheme has an approved outlay of ₹5,000 crore, including ₹700 crore for Centres of Excellence at seven NIPERs and ₹4,200 crore to accelerate R&D investment. Its stated objective is to help shift the sector from cost-based to innovation-driven growth.
The programme has subsequently expanded its emphasis on new medicines, complex generics, biosimilars and novel medical devices. In October 2025, the government said the revised programme could support an innovation pipeline of around 300 projects involving approximately ₹11,000 crore of R&D investment.
The significance of this programme should not be measured only by the number of projects funded.
The bigger test is whether India can create repeatable innovation capability.
One successful molecule does not establish an innovation ecosystem.
India needs a deeper pool of medicinal chemists, translational scientists, regulatory experts, clinical researchers, bioinformaticians, data scientists and product-development leaders.
It also needs stronger mechanisms for commercialising academic research.
This is likely to be a decade-long process, not a five-year project.
The domestic market is becoming a second engine of growth
Exports receive much of the attention, but India’s domestic pharmaceutical market presents an equally important structural opportunity.
The underlying drivers are familiar: rising healthcare expenditure, greater awareness, increased diagnosis, chronic diseases, expansion of insurance, improved access to healthcare outside major metropolitan centres and an ageing population.
The most interesting change may be the expansion of chronic and specialty therapies.
India’s healthcare system is gradually moving from a model heavily dominated by acute treatment toward one in which patients require long-term management of diabetes, cardiovascular disease, oncology, respiratory disorders and other chronic conditions.
That changes the pharmaceutical opportunity.
A patient requiring lifelong treatment creates a fundamentally different demand profile from a short-course anti-infective.
At the same time, affordability remains a constraint.
India’s pharmaceutical industry has to balance commercial growth with a healthcare system in which price sensitivity remains significant. Pricing policy, generic substitution, government procurement and access programmes will continue to shape the domestic market.
The winners are therefore unlikely to be companies that simply raise prices.
They will be companies capable of combining clinical value, affordability, brand trust and distribution reach.
Quality is becoming a competitive advantage
For many years, quality was discussed primarily as a compliance issue.
That is changing.
For a company serving global pharmaceutical customers, quality is now directly connected to revenue, customer retention, regulatory approval and valuation.
India’s revised Schedule M is part of this broader shift. The revised requirements were introduced to bring Indian GMP requirements closer to international standards, with emphasis on pharmaceutical quality systems, quality risk management, facilities, equipment and documented processes. CDSCO subsequently directed manufacturers to undertake gap analysis and compliance activities.
The significance extends beyond domestic compliance.
Global customers increasingly expect suppliers to demonstrate mature quality systems, data integrity, traceability and inspection readiness.
That means quality cannot remain the responsibility of the quality-control laboratory alone.
Senior management, engineering, production, supply chain, IT, maintenance and procurement all influence pharmaceutical quality.
A poorly maintained HVAC system can become a quality problem.
A weak data system can become a regulatory problem.
An unreliable supplier can become a batch-release problem.
A delayed deviation investigation can become a customer-confidence problem.
This is why the next generation of Indian pharmaceutical competitiveness will be closely linked to operational discipline.
Industry 4.0 will move from presentation slide to plant floor
Digital transformation in pharma has often suffered from a gap between ambition and execution.
Companies can install dashboards without improving manufacturing performance.
The next phase will be more practical.
Manufacturers are increasingly looking at MES, electronic batch records, advanced process analytics, predictive maintenance, automated visual inspection, real-time quality monitoring, digital laboratories and integrated supply-chain systems.
The value will come not from the technology itself but from what it does to the economics of manufacturing.
Can it reduce batch deviations?
Can it shorten changeover time?
Can it increase equipment utilisation?
Can it improve right-first-time performance?
Can it reduce investigation time?
Can it provide reliable data during a regulatory inspection?
These are the questions that matter.
For pharmaceutical manufacturers, Industry 4.0 should ultimately be judged through quality, cost, delivery, productivity and compliance outcomes.
The plants that genuinely integrate data into operational decision-making will have an advantage over plants that simply digitise existing paperwork.
Sustainability is moving closer to the core business
Environmental expectations are also becoming more commercially relevant.
Pharmaceutical manufacturing is resource intensive. Water, energy, solvents, effluent treatment, waste management and emissions all affect the cost and acceptability of manufacturing operations.
For companies selling into Europe and other sophisticated markets, sustainability is increasingly connected to customer expectations and supply-chain decisions.
Indian manufacturers therefore have an opportunity to treat sustainability not merely as an ESG reporting exercise but as a manufacturing-improvement programme.
Energy efficiency can lower operating costs.
Solvent recovery can reduce both waste and raw-material consumption.
Water recycling can reduce dependence on freshwater.
Process intensification can reduce the environmental footprint of production.
Green chemistry can eventually improve both sustainability and economics.
The strongest companies will increasingly discover that environmental performance and manufacturing excellence can reinforce each other.
What leading Indian pharma companies are likely to do differently
The next phase will not be won by one universal strategy.
Different companies will pursue different positions.
Some will continue to build global specialty portfolios.
Some will concentrate on complex generics and injectables.
Others will deepen their API and CDMO capabilities.
Biosimilars and biologics will remain important for companies with the scientific and manufacturing infrastructure to compete globally.
The direction of travel can already be seen in company investment patterns. For example, Lupin reported FY2025–26 R&D spending of about ₹2,063 crore, or 7.5% of sales, with investment directed toward areas including respiratory products, complex injectables and biosimilars.
This illustrates an important point.
R&D is no longer simply about discovering a new molecule.
For many Indian companies, innovation can mean developing a difficult injectable, improving a delivery system, creating a biosimilar, developing a differentiated formulation or building a manufacturing process that competitors struggle to replicate.
That broader definition of innovation could prove highly relevant to India’s next growth cycle.
Where the next wave of investment is likely to go
Over the next five to ten years, investment is likely to concentrate around several capability clusters.
Complex manufacturing will attract capital because traditional oral-solid-dose capacity is increasingly commoditised.
Injectables and sterile manufacturing should remain attractive because technical and regulatory barriers are higher.
Biosimilars and biologics will receive investment as healthcare systems look for ways to manage the cost of advanced therapies.
APIs and intermediates will remain strategically important because supply security has become a board-level issue.
CDMO and CRDMO should continue to attract capital as multinational companies diversify development and manufacturing networks.
Digital manufacturing will expand as companies look for productivity improvements and stronger data integrity.
And R&D infrastructure will receive increasing attention as companies seek differentiated products rather than relying entirely on conventional generics.
The common thread is clear: capital is moving toward capabilities that are harder to replicate.
The risks India cannot ignore
There is a danger in interpreting every positive trend as proof that India’s pharmaceutical industry is guaranteed to dominate.
It is not.
Regulatory observations can still disrupt manufacturing operations and damage customer confidence.
Quality failures can erase years of commercial development.
Pricing pressure remains severe in many generic markets.
China retains enormous manufacturing scale in several chemical and pharmaceutical-input categories.
Advanced biologics and novel therapies require capabilities that cannot be developed simply by spending more money on buildings and equipment.
India also faces a shortage of specialised scientific and technical talent in some advanced fields.
And perhaps most importantly, capital expenditure can become counterproductive if companies build capacity faster than sustainable demand.
The industry’s history contains enough examples to demonstrate that capacity without utilisation is not growth.
The next decade therefore requires more disciplined capital allocation.
Companies will need to ask not simply, “Can we build this facility?” but “What differentiated capability will this facility give us, who will buy it, and why will they continue buying from us?”
What the next five to ten years could look like
The most likely future is not one in which India abandons generics and suddenly becomes a global innovator.
That would be unrealistic.
Instead, the Indian pharmaceutical industry is likely to develop into a more diversified ecosystem.
Generics will remain the foundation.
Around that foundation will grow complex generics, specialty medicines, biosimilars, APIs, advanced manufacturing, CDMO/CRDMO services and selected areas of innovative drug development.
This is already reflected in the industry’s export ambitions.
A Bain & Company report developed with Pharmexcil, IPA and IDMA estimates that India’s pharmaceutical exports could reach US$60–65 billion by 2030, with biosimilars, APIs and innovative products expected to account for a greater proportion of the mix. These are projections rather than guarantees, but they illustrate the scale of the opportunity being considered by industry stakeholders.
The critical issue is therefore not whether India will grow.
It is what kind of growth India will capture.
If the industry remains heavily dependent on price competition, growth will eventually encounter margin pressure.
If it develops proprietary capabilities, stronger quality systems, complex manufacturing, scientific depth and trusted global relationships, the economic value of that growth could be considerably greater.
The real competitive advantage will be trust
There is a broader lesson in India’s pharmaceutical opportunity.
For years, the country’s competitive advantage was described in terms of cost.
Cost will remain important. But it is becoming less sufficient.
Global pharmaceutical companies increasingly need suppliers who can provide something more difficult to quantify: confidence.
That a manufacturing process will remain under control.
That data can withstand regulatory scrutiny.
That intellectual property will be protected.
That a complex product can be scaled.
That supply will continue during geopolitical disruption.
That a development programme will meet its milestones.
That is why India’s next pharmaceutical advantage may ultimately be built on trust backed by capability.
The country’s large manufacturing base provides the starting point. Its scientific talent provides another layer. Government policy is increasingly directing capital toward self-reliance, R&D and innovation. Global supply-chain diversification provides a favourable external environment.
But none of these factors guarantees success.
The companies that capture the next wave will be those capable of converting them into consistent execution.
The opportunity ahead
India’s pharmaceutical industry has already proved that it can manufacture medicines at scale and compete successfully in some of the world’s most demanding markets.
The next challenge is considerably more ambitious.
It is to become indispensable not merely because India offers a lower manufacturing cost, but because Indian companies can provide quality, scientific capability, speed, flexibility, regulatory confidence and reliable global supply.
That is a much more valuable position.
The coming decade could therefore mark a significant change in the character of Indian pharma. The industry may remain deeply rooted in generics, but its growth engine is likely to become more diversified — extending into complex products, biologics, CDMO/CRDMO, APIs, advanced manufacturing and innovation.
For manufacturers, the message is straightforward: capacity alone will not be enough.
For investors, the distinction between commodity capacity and differentiated capability will become increasingly important.
For policymakers, the next priority is to ensure that incentives create globally competitive businesses rather than simply additional domestic capacity.
And for pharmaceutical professionals, the skills required by the industry are changing rapidly — from traditional production and quality expertise toward data, automation, process science, regulatory intelligence, advanced manufacturing and cross-functional problem solving.
India’s pharmaceutical opportunity is therefore larger than the next generic product launch or the next manufacturing plant.
It is the opportunity to build a deeper, more sophisticated and more resilient pharmaceutical ecosystem.
Whether India captures that opportunity at scale will depend on what the industry does with its existing advantages.
The next chapter will be less about proving that India can manufacture medicines.
It will be about proving that India can consistently manufacture, develop and deliver higher-value medicines to the world with a level of quality and reliability that global customers are willing to build their businesses around.
Key Takeaways
- India’s pharma expansion is shifting from volume-led to capability-led growth, with complex generics, biosimilars, injectables, APIs and specialty products gaining strategic importance.
- Supply-chain diversification is creating a major opportunity, particularly in CDMO/CRDMO and advanced manufacturing, but India is more likely to complement than completely replace China.
- Government policy is increasingly supporting both self-reliance and innovation, with substantial programmes for APIs, manufacturing and pharmaceutical R&D.
- Quality and regulatory reliability are becoming competitive advantages, not merely compliance requirements, particularly as Indian companies seek deeper relationships with global pharmaceutical customers.
- The biggest opportunity over the next decade is not simply more capacity; it is higher-value capability — combining manufacturing scale with science, technology, quality, R&D and global customer trust.
Reference
- Department of Pharmaceuticals, Government of India — PRIP scheme and pharmaceutical-sector programmes.
- Economic Survey 2025–26 — pharmaceutical-sector turnover, exports and India’s movement toward higher-value products.
- Pharmexcil — FY2024–25 pharmaceutical export performance and export composition.
- Bain & Company / Pharmexcil / IPA / IDMA — roadmap for India’s pharmaceutical exports through 2030 and beyond.
- CDSCO — revised Schedule M and GMP implementation requirements.
- CRISIL Ratings — Indian CRDMO growth, supply-chain diversification and competitive advantages.
- Government of India / PIB — PLI and pharmaceutical R&D implementation updates.
- Lupin Integrated Report FY2025–26 — example of increasing R&D focus on complex products, injectables and biosimilars.